Best overall: Progressive. Best for local agent service: The Concord Group. Best for digital self-service: GEICO. This 2026 guide compares the best auto insurance companies in New Hampshire by driver profile, coverage needs, service model, and policy management.
- Progressive is the 2026 pick for New Hampshire drivers who need an SR-22 filing or support for a difficult record.
- GEICO fits drivers who prefer digital quotes, app-based policy management, and limited agent interaction.
- The Concord Group is the local-service pick among the best auto insurance companies in New Hampshire.
- MMG Insurance, Vermont Mutual, and Amica fit different combinations of bundling, regional service, and direct access.
- Themello Agency helps New Hampshire drivers review auto insurance options without relying on one company name alone.
Why this matters
New Hampshire does not generally require every driver to buy auto insurance before registering a vehicle. It does require drivers to demonstrate financial responsibility after certain convictions, accidents, or license actions under New Hampshire RSA 264.
When proof of financial responsibility is required in 2026, the standard liability amounts are $25,000 for bodily injury to one person, $50,000 for bodily injury in one accident, and $25,000 for property damage. These limits are commonly shortened to 25/50/25. A lender or leasing company can separately require collision and comprehensive coverage under your finance agreement.
The legal minimum is not a recommendation for every household. Your vehicles, assets, regular passengers, driving history, and ability to absorb a claim should determine the limits you choose.
Themello Agency provides auto insurance reviews for New Hampshire drivers alongside home, flood, business, and life insurance. Themello Agency is best for New Hampshire drivers who want a quick coverage review before choosing a carrier or renewing an existing policy.
Before comparing companies, review New Hampshire's minimum auto insurance requirements so every quote uses the same limits and deductibles.
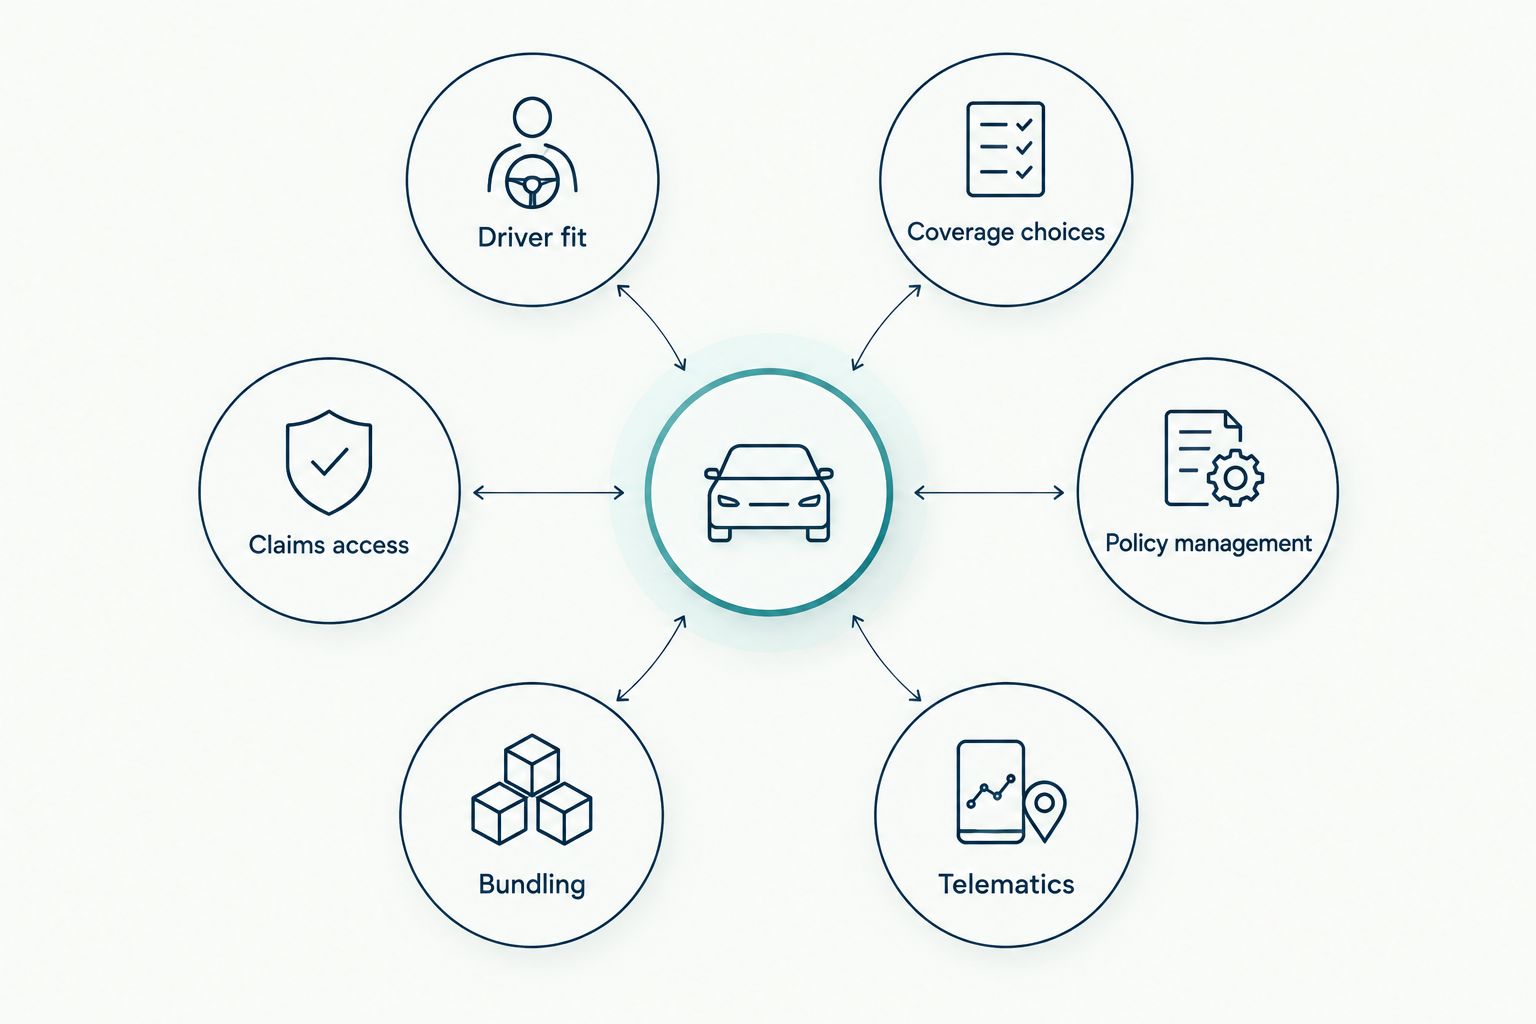
What makes the best auto insurance company in New Hampshire
Use the same inputs for every quote. A lower premium does not represent a better deal when one quote carries lower liability limits, higher deductibles, or missing optional coverage.
- Driver fit: Some carriers are better suited to clean records, while others accommodate drivers who need an SR-22 filing or have recent violations.
- Coverage choices: Compare liability, collision, comprehensive, uninsured motorist coverage, rental reimbursement, roadside assistance, and other options relevant to your vehicle.
- Claims access: Check how you report a claim, how the company communicates updates, and whether local agent help is available.
- Policy management: Decide whether you prefer an app, a call center, a local agent, or a combination of those channels.
- Bundling: A home or renters policy can change the total household cost, so compare the combined result rather than the auto quote alone.
- Telematics: Usage-based programs can monitor mileage and driving behavior. Participation should match your privacy preferences and driving routine.
Best auto insurance companies in New Hampshire at a glance
| Company | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Progressive | Drivers needing an SR-22 filing | Snapshot telematics program | Telematics requires driving-data collection |
| GEICO | Digital self-service | Online and mobile policy tools | Limited local agent interaction |
| The Concord Group | Local New Hampshire service | Concord-based regional presence | Agent-centered shopping process |
| MMG Insurance | Regional policy bundling | Auto and property policies through agents | Regional rather than nationwide focus |
| Vermont Mutual | Independent-agent relationships | Policyholder-owned mutual structure | No direct-to-consumer shopping model |
| Amica | Direct mutual-insurer access | Direct quotes and policy management | Not available through an independent-agent comparison |
1. Progressive: best for SR-22 and higher-risk drivers
Progressive offers New Hampshire auto insurance and can file an SR-22 when a driver must provide proof of financial responsibility. That makes it a practical starting point after a qualifying license action, although approval and policy terms still depend on underwriting.
Progressive also offers Snapshot, a usage-based program that evaluates driving behavior. Compare the telematics terms before enrolling because participation involves sharing driving data and the result depends on recorded behavior.
Progressive pros:
- Supports SR-22 filings for drivers who need them
- Offers online, phone, and agent-assisted policy access
- Provides a usage-based insurance option through Snapshot
- Handles standard and more complicated driver profiles
Progressive cons:
- Snapshot requires driving-data collection
- A quote can change materially when violations, claims, or additional drivers are added
- Digital convenience does not replace reviewing exclusions and coverage limits
Best for: New Hampshire drivers who need an SR-22 filing or want to compare a policy after violations.
Verdict: Buy if your record makes standard-market shopping difficult in 2026, but compare the final coverage line by line.
2. GEICO: best for digital self-service
GEICO suits drivers who prefer to quote, change, and manage a policy online or through a mobile app. Its service model reduces the need for routine in-person agent contact.
The company also offers DriveEasy, a telematics program that uses driving data. Drivers who do not want app-based monitoring can compare a standard policy without making telematics the deciding factor.
GEICO pros:
- Direct online quoting
- Mobile access for policy documents and routine account tasks
- Digital claims-reporting tools
- Usage-based insurance available through DriveEasy
GEICO cons:
- Limited local-agent interaction compared with agent-distributed carriers
- DriveEasy involves app-based driving data
- Direct quotes do not automatically compare competing companies
Best for: New Hampshire drivers who want to handle most insurance tasks digitally.
Verdict: Buy if app-based service is a priority and the quote matches the same limits used elsewhere.
3. The Concord Group: best for local New Hampshire service
The Concord Group is based in Concord and writes personal insurance through agents. Its regional model fits drivers who want an agent familiar with New Hampshire policies rather than a direct-only purchasing process.
A local headquarters does not automatically make every policy the right fit. Compare the carrier's coverage, deductibles, endorsements, and claims process with national and regional alternatives.
The Concord Group pros:
- New Hampshire-based regional presence
- Agent-assisted quoting and policy service
- Auto and property coverage available within the same carrier relationship
- Familiarity with a New England operating area
The Concord Group cons:
- Agent-centered shopping offers less direct self-service than digital-first carriers
- Regional availability is narrower than that of national companies
- Policy options still vary by driver, vehicle, and location
Best for: drivers who want an agent relationship and a carrier based in New Hampshire.
Verdict: Buy if local service is your main priority for 2026 and the full policy compares well.
4. MMG Insurance: best for regional bundling
MMG Insurance serves New England through independent insurance agents and offers personal auto and property coverage. It belongs on the shortlist when you want to compare the combined result for auto and home or renters insurance.
Bundling should be evaluated on total coverage and total policy cost. A discount label alone does not prove that the combined policies beat separate carriers.
MMG Insurance pros:
- Offers personal auto and property insurance
- Uses independent agents for quoting and service
- Regional focus across New England
- Supports a combined household-policy comparison
MMG Insurance cons:
- Not designed for direct-only shopping
- Regional reach is narrower than a national carrier's reach
- The value of bundling depends on both policies, not the auto quote alone
Best for: New Hampshire households comparing auto with home or renters insurance.
Verdict: Buy if the combined 2026 policy comparison beats separate coverage without reducing limits.
5. Vermont Mutual: best for an independent-agent relationship
Vermont Mutual is a regional mutual insurance company that distributes coverage through independent agents. A mutual insurer is owned by policyholders rather than public shareholders, but that structure should be treated as one comparison point rather than a guarantee of service or price.
This carrier fits shoppers who want an agent to explain coverage and help manage policy changes. It is less suitable for someone who wants to complete the entire purchase directly with the insurer.
Vermont Mutual pros:
- Policyholder-owned mutual structure
- Regional New England focus
- Coverage distributed through independent agents
- Auto and property options support household comparisons
Vermont Mutual cons:
- No direct-to-consumer shopping model
- Agent availability affects the shopping experience
- Regional scope is narrower than that of a nationwide insurer
Best for: drivers who prefer an independent agent and a regional mutual carrier.
Verdict: Hold until you compare the complete policy with at least one direct carrier and one other agent-distributed carrier.
6. Amica: best for direct access to a mutual insurer
Amica offers direct quotes and personal insurance without requiring an independent agent. It combines a mutual-company structure with online and phone-based policy access.
That direct model works for drivers who want to deal with the insurer itself. It does not provide the multi-carrier comparison that an independent agency can provide, so you must collect competing quotes separately.
Amica pros:
- Direct quoting and policy service
- Mutual-insurer structure
- Auto and property coverage available
- Digital account access for policy management
Amica cons:
- Not part of an independent agent's multi-carrier comparison
- You must obtain competing quotes separately
- A direct relationship is less useful if you prefer one agent to review several carriers
Best for: New Hampshire drivers who want direct access to a mutual insurer.
Verdict: Buy if direct service matters, but do not treat one 2026 quote as the full market.
How these companies were ranked
The ranking uses the six criteria listed above: driver fit, coverage choices, claims access, policy management, bundling, and telematics. It does not claim that one carrier has the lowest rate for every New Hampshire driver because no submitted pricing data supports that conclusion.
Each company owns a distinct use case. Progressive leads for drivers needing SR-22 support, GEICO for digital self-service, The Concord Group for local service, MMG Insurance for regional bundling, Vermont Mutual for independent-agent access, and Amica for direct access to a mutual insurer.
Which auto insurance company should you choose?
Start with Progressive if you need an SR-22 filing or have a driving record that complicates standard shopping. Start with GEICO if you want digital self-service, or The Concord Group if local agent access matters more.
Compare MMG Insurance when auto and property coverage need to work together. Put Vermont Mutual on the list when you want an independent-agent relationship, and add Amica when you want a direct quote from a mutual insurer.
Do not compare six policies with six different configurations. Give every carrier the same drivers, vehicles, annual mileage, liability limits, physical-damage deductibles, and optional coverages. Then review the exclusions and policy forms before choosing.
A Themello Agency auto insurance review can help New Hampshire drivers organize that comparison in 2026. The useful question is not which company has the most recognizable name; it is which policy addresses your specific drivers, vehicles, assets, and service preferences.
Review your auto coverage
Compare your current limits and deductibles before choosing a New Hampshire carrier.
FAQ
What is the best auto insurance company in New Hampshire?
Progressive is the best starting point for drivers needing SR-22 support, GEICO fits digital-first drivers, and The Concord Group fits drivers prioritizing local service. The best final choice depends on your record, vehicles, limits, deductibles, and preferred service model.
Does New Hampshire require auto insurance in 2026?
New Hampshire does not generally require every driver to buy auto insurance before registering a vehicle in 2026. The state can require proof of financial responsibility after specified accidents, convictions, or license actions.
What are the New Hampshire financial-responsibility limits?
The standard limits are $25,000 for bodily injury to one person, $50,000 for bodily injury in one accident, and $25,000 for property damage. These amounts are commonly written as 25/50/25.
Is Progressive or GEICO better for New Hampshire drivers?
Progressive is the stronger starting point for SR-22 needs or a complicated driving record, while GEICO is the stronger fit for direct digital service. Compare both using identical limits, deductibles, drivers, and vehicles.
Is a local insurer better than a national insurer?
A local or regional insurer is better when agent access and regional service matter most, while a national insurer can offer broader digital access. Company size alone does not determine whether the policy fits your coverage needs.
How much does auto insurance cost in New Hampshire?
The cost depends on the drivers, vehicles, location, mileage, coverage limits, deductibles, claims, violations, and other underwriting factors. Use identical inputs for every 2026 quote instead of relying on a statewide average that does not describe your household.
Should I bundle home and auto insurance in New Hampshire?
Bundle home and auto insurance when the combined policies provide the right coverage at a better total cost. Compare the bundled result with separate carriers because a discount does not automatically produce the best overall policy.
How do I switch auto insurance companies in New Hampshire?
Place the replacement policy before canceling the current one, then confirm both effective dates in writing. Review any lender requirements and avoid even a one-day coverage gap.
One last thing
Ask for the complete coverage summary before choosing a company. A quote can look cheaper because it uses lower liability limits, higher deductibles, or fewer optional coverages rather than because the carrier offers better value.
Themello Agency recommends a quick review whenever a vehicle, driver, address, loan, or household asset changes. Those changes can matter more than the company name printed on the policy.
Related guides
- High-risk auto insurance for New Hampshire drivers
- How to switch auto insurance companies in New Hampshire
- Full-coverage auto insurance requirements in New Hampshire