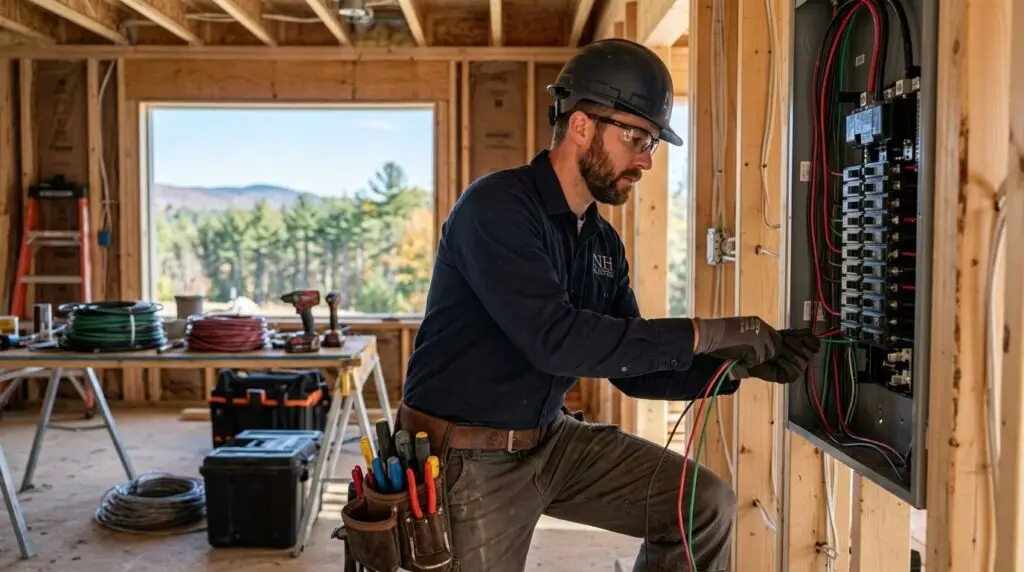
Electrician insurance in New Hampshire combines general liability, workers' compensation, and commercial auto coverage built around the specific hazards of running wire, working live panels, and hauling tools between job sites. A one-person electrical outfit in Concord has different exposure than a five-truck crew wiring new construction in Nashua, and a policy that ignores that difference leaves gaps exactly where claims happen.
The biggest difference between electricians and other trades is the severity of a single mistake. A miswired panel or a fire traced back to your work can trigger a six-figure claim, not a small repair bill, which is why liability limits and equipment coverage matter more here than for most contractors. Business insurance for contractors in New Hampshire covers the general contractor version of this; electricians need the same foundation plus coverage tuned to electrical risk specifically.
- Electrician insurance NH starts with general liability plus workers’ compensation once you have employees on payroll.
- Tool and equipment coverage through inland marine protects gear that moves between job sites daily, where standard property policies fall short.
- A business owners policy bundles liability and property for small electrical shops but often caps limits too low for commercial jobs.
- Umbrella coverage matters most for electricians bidding new construction or commercial panel work where claim size jumps fast.
Why electrician insurance matters in New Hampshire
New Hampshire requires workers' compensation for any business with employees, including part-time help, and licensed electricians working under a master license carry personal liability exposure that follows them from job to job. General contractors and property managers in NH increasingly require proof of liability coverage before they'll hand over a subcontract, so a certificate of insurance isn't optional paperwork anymore, it's the price of getting on the job.
Electrical work also sits higher on underwriters' risk tables than carpentry or painting because of fire and electrocution exposure. That pushes premiums up compared to lower-risk trades, but it also means skipping coverage or underinsuring puts your license, your trucks, and your personal assets on the line if a claim exceeds your limits.
Build coverage that matches how electricians actually work
Carry general liability sized to your job type
General liability is the base layer for any electrician, covering property damage and bodily injury claims tied to your work. Residential rewiring jobs and commercial panel installs carry different risk profiles, so limits should scale with the size of the contracts you're bidding.
- Confirm your policy covers completed operations, not just active work on site
- Check that limits meet what general contractors require for subcontract work
- Verify coverage extends to work performed at multiple job sites, not one fixed location
- Ask whether faulty workmanship claims are excluded or included
- Review aggregate limits against your typical annual job volume
Add workers' compensation once you hire your first employee
New Hampshire law requires workers' compensation coverage the moment you have even one employee, and electricians face higher injury rates than office-based businesses due to ladder work, live circuits, and confined spaces. Workers' compensation insurance for New Hampshire small businesses breaks down how classification codes affect what electricians pay.
- Classify employees correctly under electrician-specific codes, not general labor
- Include apprentices and part-time helpers, not just full-time staff
- Confirm coverage applies across all NH job sites, not one address
- Review experience modification factors annually as claims history changes
- Ask about return-to-work programs that reduce claim costs after an injury
Insure your service vehicles the right way
A personal auto policy typically excludes business use, which means your van full of conduit and breakers isn't covered under a personal plan the moment you're driving to a job. Commercial auto coverage protects the vehicle, the tools inside it, and third-party damage if you're at fault in an accident. Commercial auto insurance for New Hampshire business fleets covers this for electricians running one truck or a full fleet.
- Cover every vehicle titled to the business, including older trucks kept as backups
- Confirm hired and non-owned auto coverage if employees use personal vehicles for work
- Check that tools stored in the vehicle are covered under the auto policy or a separate rider
- Review liability limits against the size of vehicles you operate
- Ask about coverage for towing equipment or trailers hauling bucket trucks
Cover tools and equipment that move between job sites
Electricians carry expensive meters, benders, and specialty tools that rarely sit in one place long enough for standard commercial property insurance to make sense. Inland marine coverage follows the equipment instead of a fixed location, which fits how electrical contractors actually operate. Inland marine insurance for New Hampshire contractors is built around exactly this gap.
- List high-value tools individually rather than relying on a blanket limit
- Confirm coverage applies whether tools are in the truck, on site, or in storage
- Check theft coverage specifically, since job site tool theft is common in the trades
- Review replacement cost versus actual cash value terms
- Ask whether rented or borrowed equipment is included
Bundle coverage through a business owners policy where it fits
A business owners policy combines general liability and commercial property into one package, which simplifies management for a small electrical shop running one or two crews. It's not built for every electrician, though, especially those bidding larger commercial contracts that need higher limits than a BOP typically offers.
- Compare BOP liability limits against what commercial general contractors require
- Confirm the property portion covers your shop, office, or storage building
- Check whether tool and equipment coverage is included or needs a separate rider
- Ask if business interruption coverage is part of the package
- Review whether the BOP scales as you add employees or vehicles
Add umbrella coverage before bidding bigger jobs
An umbrella policy sits on top of your general liability and auto coverage, extending your limits when a claim exceeds what the underlying policy pays. Electricians moving into commercial or new construction work should look at this before, not after, taking on a job where a single claim could exceed standard limits. Umbrella insurance for New Hampshire business owners explains how the layering works.
- Confirm the umbrella follows both your general liability and commercial auto policies
- Check that limits match the size of contracts you're now bidding
- Review whether the umbrella covers completed operations claims that surface after a job ends
- Ask if coverage extends to employees, not just the business entity
Review coverage every time your business changes
Adding a second truck, hiring your first employee, or moving into commercial panel work all shift your risk profile, and a policy written for a solo operator doesn't automatically cover a five-person crew. Set a fixed review point, not a vague someday.
- Review coverage at every renewal, not just when something goes wrong
- Update the policy the same month you hire, not months later
- Reassess limits after landing a contract significantly larger than your usual jobs
- Confirm subcontractors you hire carry their own coverage, so their risk doesn't fall on you
Get your electrician policy reviewed
Quick review of your current coverage, no pressure.
Comparing coverage options for NH electricians
| Option | Best for | Key limitation |
|---|---|---|
| General liability only | Solo electricians doing small residential jobs | No coverage for employees, tools in transit, or vehicles |
| Business owners policy | Small shops with one location and modest limits needs | Limits often too low for commercial contracts |
| GL plus workers' comp bundle | Electricians with one or more employees | Doesn't cover tools, vehicles, or umbrella-level claims |
| Full commercial package (GL, WC, auto, inland marine) | Growing crews bidding commercial and new construction work | Requires more paperwork and annual review as the business scales |
The full commercial package is the right call for any electrician with employees, a service vehicle, and job sites outside a single fixed address, which describes most working electricians in New Hampshire by year two.
Common mistakes electricians make with coverage
- Skipping workers' comp for part-time help — New Hampshire law doesn't carve out an exception for a helper working 15 hours a week.
- Relying on personal auto insurance for the work van — a claim gets denied the moment the adjuster sees tools and a business logo on the vehicle.
- Underinsuring tools with a blanket property limit — a stolen $3,000 meter set doesn't get replaced under a generic $2,000 cap.
- Waiting until a contract requires proof of insurance — scrambling to bind a policy the week before a job starts often means paying more and missing coverage gaps in the rush.
- Not updating limits after moving into commercial work — a residential-sized policy doesn't stretch to cover a claim on a commercial build-out.
FAQ
What insurance do electricians need in New Hampshire?
Electricians in New Hampshire need general liability insurance at minimum, and workers’ compensation the moment they hire even one employee. Commercial auto and tool coverage through inland marine round out a full policy for anyone driving to job sites daily.
Is workers’ compensation required for electricians in NH?
Yes, New Hampshire law requires workers’ compensation coverage for any business with employees, including part-time and apprentice workers. Solo electricians with no employees aren’t required to carry it but can still opt in for personal injury protection.
Does a business owners policy cover electricians?
A business owners policy covers small electrical shops running modest liability and property needs, but limits are often too low for commercial contracts. Electricians bidding larger jobs typically need a full commercial package with higher limits instead.
How much does electrician insurance cost in New Hampshire?
Cost depends on crew size, vehicle count, and the type of work performed, since commercial and new construction jobs carry higher risk than residential service calls. A quick coverage review is the fastest way to get an accurate number for your specific business.
Do electricians need tool insurance separate from general liability?
Yes, general liability doesn’t cover stolen or damaged tools. Inland marine coverage is built specifically for equipment that moves between job sites, which fits how most electricians operate day to day.
Can electricians get commercial auto insurance for one truck?
Yes, commercial auto policies cover single-vehicle operations as well as full fleets. A personal auto policy typically excludes business use, so even a one-truck electrician needs commercial coverage once the vehicle is used for work.
When should an electrician add umbrella insurance?
Umbrella coverage matters most once an electrician starts bidding commercial or new construction contracts, where a single claim could exceed standard liability limits. It’s worth adding before taking on that first larger job, not after.
What happens if an electrician works without insurance in NH?
Working without required workers’ compensation violates New Hampshire law and exposes the business owner to direct liability for injury costs. Without general liability, a single claim from faulty work or property damage can be paid entirely out of pocket.
One last thing
The most overlooked gap isn't liability or workers' comp, it's completed operations coverage that protects against a claim surfacing months after a job wraps, like a fire traced back to wiring installed the previous year. Confirm that clause specifically before signing anything in 2026, because it's the coverage electricians reach for most and check for least.
Related guides
- General liability insurance for New Hampshire small businesses
- How to choose a business owners policy in New Hampshire
- Business insurance for HVAC contractors in New Hampshire
- Employment practices liability insurance in New Hampshire