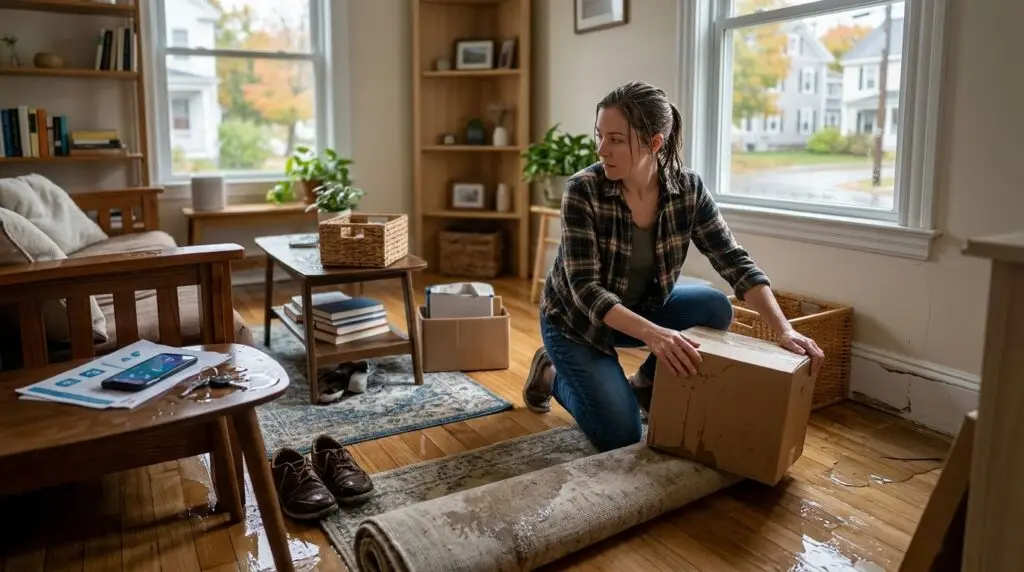
Flood insurance for renters in New Hampshire covers your personal belongings against flood damage that a standard renters policy excludes outright, and it's coverage your landlord's insurance will never extend to your side of the lease. Renters near Lake Winnipesaukee, the Merrimack River, the Connecticut River, or the coastal towns of Hampton and Rye face a real gap: their landlord's building may carry flood coverage, but nothing in that policy touches a tenant's furniture, electronics, or clothing.
- Standard NH renters insurance (HO-4) excludes flood damage to your belongings entirely, no matter the carrier.
- NFIP contents-only flood policies cover renters’ personal property up to $100,000 in 2026.
- NFIP flood insurance typically takes 30 days to take effect, so buy before spring snowmelt or hurricane season, not during it.
- Private flood carriers can offer higher limits or skip the waiting period in some cases.
- Verdict: renters near NH lakes, rivers, or the coast need a standalone flood insurance for renters NH policy, not just contents coverage bundled with a landlord’s building policy.
Why flood insurance matters for New Hampshire renters
A renters insurance for New Hampshire tenants policy protects belongings from fire, theft, and certain water damage like a burst pipe. It does not touch flood damage from rising water, storm surge, or overflowing rivers and lakes. That distinction matters more in New Hampshire than in a lot of states because so much of the rental housing stock sits close to water: lakefront cottages converted to year-round rentals, riverside apartment buildings in Manchester and Concord, and coastal units in Hampton and Rye that sit inside FEMA-mapped flood zones.
Spring snowmelt and heavy rain events push river levels up fast in New Hampshire, and a Special Flood Hazard Area designation on FEMA's flood maps doesn't care whether you own the building or rent the third floor. If you rent in a mapped zone and skip flood coverage, a single flood event can wipe out your furniture, electronics, and clothing with zero payout from your landlord's policy or your own renters policy.
Check your flood zone before you sign a lease
Do this before you rent, not after the water's in your closet.
- Pull the FEMA Flood Map Service Center report for the exact street address, not just the town name
- Ask the landlord directly whether the unit or building has flooded before
- Confirm whether the property sits in a Special Flood Hazard Area (SFHA) or a moderate-risk zone
- Note your floor level: a basement or ground-floor unit near water carries materially higher risk than a third-floor unit in the same building
- Check proximity to known NH flood sources: the Merrimack River, the Connecticut River, Lake Winnipesaukee, and coastal marshland near Hampton
Read your renters policy's flood exclusion line by line
Most renters assume "water damage" coverage means flood coverage. It doesn't.
- Pull your HO-4 declarations page and find the water damage section specifically
- Separate "water backup" (a sewer or drain backing up, often covered) from "flood" (surface water entering from outside, never covered)
- Ask your agent to point to the exact exclusion clause in plain language, not policy jargon
- Check whether sewer or drain backup is a built-in coverage or a separate add-on you'd need to request
Get a contents-only flood quote
Once you know your flood zone and confirmed your renters policy excludes flood, get a quote built for a tenant, not a homeowner.
- Request an NFIP "Renters/Contents-only" flood policy quote for the exact unit address
- Get a private flood carrier quote for comparison
- Do a quick inventory of your belongings first so the quote isn't guessing at coverage amounts
- Confirm whether the quote pays replacement cost or actual cash value on electronics and furniture
- Ask whether the quote includes coverage for items stored below ground level, since basement storage often has separate sub-limits
Time your purchase around the 30-day waiting period
NFIP flood policies don't activate the day you buy them.
- Buy flood coverage well before spring snowmelt season or an active storm forecast
- Remember the standard NFIP waiting period runs 30 days from purchase before coverage takes effect
- Check whether a mortgage-related exception applies (it usually doesn't for renters, since renters aren't financing the property)
- Ask a private carrier whether their waiting period is shorter, since some private flood policies activate faster than NFIP
- Set a calendar reminder to renew before the policy lapses, since a lapse resets the waiting period clock
Decide between NFIP and private flood coverage
Both cover contents. They don't cover it the same way.
- Compare the coverage cap: NFIP tops out at $100,000 for renters' contents, private carriers may go higher
- Compare deductible options: private carriers often offer more flexible deductible tiers
- Check claims history and payout speed if the carrier publishes it
- Confirm whether the private option covers additional living expenses if the flood forces a temporary move
Bundle flood coverage with your renters insurance
A flood policy and a renters policy are separate products, but pairing them with one agent simplifies claims.
- Ask your agent to review your existing renters insurance for New Hampshire tenants coverage alongside any new flood quote
- Confirm both policies use matching contents valuation (replacement cost vs. actual cash value) so there's no gap between them
- Ask whether combining carriers changes your renters premium at all
- Keep both declarations pages together so a claims adjuster isn't guessing which policy applies
Document your belongings before you ever file a claim
This step costs nothing and it's the one renters skip most.
- Photograph or video every room, including closets and storage areas
- Keep digital copies of receipts for major purchases: electronics, furniture, appliances
- Store the inventory somewhere outside the apartment (cloud storage, email to yourself)
- Update the inventory once or twice a year, not just when you move in
Comparing flood coverage options for NH renters
| Option | Best for | Key limitation |
|---|---|---|
| NFIP Renters/Contents-only policy | Renters wanting a federally backed, standardized policy | Coverage caps at $100,000 for contents, no dwelling coverage needed since you don't own the structure |
| Private flood insurance | Renters wanting higher limits or faster activation | Availability and terms vary by carrier and zip code |
| Standard renters insurance (HO-4) alone | Renters not in a flood zone at all | Excludes flood damage entirely, no exceptions |
| Landlord's building flood policy | Covers the structure only | Never covers a tenant's personal belongings under any circumstance |
The one sentence to remember: a landlord's flood policy protects the walls, not what's inside your apartment, and only a renters-specific flood policy fixes that gap.
Common mistakes New Hampshire renters make
- Assuming the landlord's flood insurance covers them. It covers the building's structure, never a tenant's furniture or electronics.
- Buying flood coverage after a storm warning goes out. The 30-day NFIP waiting period means that purchase does nothing for the storm already on the forecast.
- Skipping flood coverage because "renters don't need it." Anyone renting in a mapped flood zone near the Merrimack River, Lake Winnipesaukee, or the coast carries the same flood exposure a homeowner does, just for contents instead of structure.
- Underestimating what's actually at risk. A laptop, a mattress, a closet of clothing, and a kitchen's worth of appliances add up fast once you price replacement cost instead of guessing.
- Not checking flood zone status before signing a lease. Once you've moved in and paid a deposit, you're stuck with whatever flood risk the address carries.
Compare that against landlord-side coverage too: if you're weighing whether your landlord's landlord insurance for New Hampshire rental property owners policy includes flood protection for the building, ask directly, because that policy still won't extend to your belongings.
“A landlord’s flood policy protects the walls, not what’s inside your apartment.”
Renters near the water aren't the only New Hampshire residents facing this gap. Owners of lakefront property who carry flood insurance for New Hampshire lake homes deal with the same NFIP mechanics, just on the dwelling side instead of the contents side.
Get your NH flood quote started
Quick review of your renters and flood coverage, no pressure.
FAQ
What’s the best flood insurance for renters in New Hampshire?
An NFIP Renters/Contents-only policy is the standard option for New Hampshire tenants in 2026, covering personal belongings up to $100,000. A private flood carrier can be a better fit if you need higher limits or a shorter waiting period.
Does renters insurance cover flood damage in NH?
No. Standard HO-4 renters insurance in New Hampshire excludes flood damage entirely, regardless of carrier. You need a separate flood policy to cover belongings damaged by rising water.
How much does flood insurance cost for renters in New Hampshire?
Cost depends on your flood zone designation, coverage amount, and deductible choice, and it varies by carrier. Get a quick review from an agent using your exact address rather than a general estimate.
Is flood insurance required for renters in New Hampshire?
Flood insurance isn’t legally required for renters the way auto insurance is, but a landlord in a high-risk flood zone may require tenants to carry it as a lease condition. Check your lease terms directly.
How long does it take for flood insurance to go into effect?
Most NFIP flood policies carry a standard 30-day waiting period before coverage starts. Some private flood carriers offer shorter activation windows, so ask directly when comparing quotes.
Does my landlord’s flood insurance cover my belongings?
No. A landlord’s flood policy covers the building structure only. Your furniture, electronics, and clothing need a separate renters flood policy to be covered.
What’s covered under a contents-only flood policy?
A contents-only flood policy covers personal belongings like furniture, electronics, clothing, and appliances damaged by flood water, up to the policy limit. It does not cover the building structure, since that’s the landlord’s responsibility.
Is private flood insurance better than NFIP for renters?
It depends on your coverage needs. NFIP offers a standardized, federally backed policy capped at $100,000 for contents, while private carriers can offer higher limits or faster activation but vary by zip code and carrier.
One last thing
The NFIP's $100,000 contents cap is a ceiling, not a guaranteed payout. Most contents policies settle claims at actual cash value unless you specifically request replacement cost coverage, which means a five-year-old couch or laptop gets valued at its depreciated worth, not what it costs to replace in 2026. Ask for replacement cost coverage by name when you get a quote, because the default setting on most policies isn't in your favor.
Related guides
- Renters insurance for New Hampshire tenants
- Landlord insurance for New Hampshire rental property owners
- Flood insurance for New Hampshire lake homes
- Home insurance for New Hampshire coastal properties
- Flood insurance for New Hampshire businesses