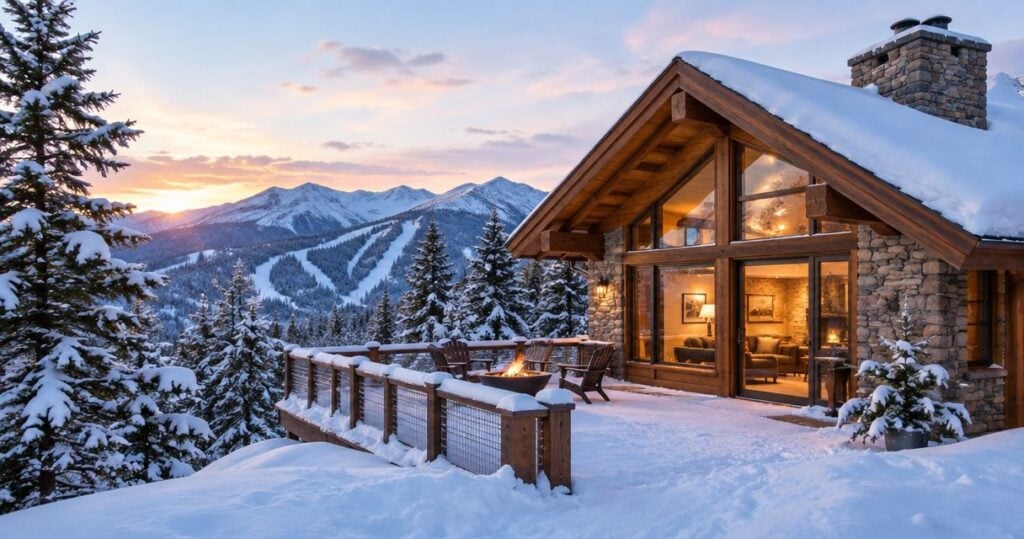
New Hampshire's ski chalets and mountain properties carry risks a standard homeowners policy in Manchester or Nashua never has to think about: heavy roof snow load, wood stove heat, and months with nobody home between visits. This guide ranks the coverage options that actually protect a mountain property in 2026, not just whichever quote comes back cheapest.
Best overall: high-value home insurance for chalets with high rebuild costs. Best for part-time owners: seasonal camp coverage. Best for absentee owners: vacant home coverage. Best for owners who live outside New Hampshire: vacation home insurance for out-of-state owners.
- High-value home insurance is the best home insurance for a New Hampshire ski chalet with custom finishes and a high rebuild cost.
- Seasonal camp coverage fits chalets used only part of the year; a standard policy can leave gaps during the off months.
- Vacant home coverage matters most once a mountain property sits empty for weeks at a stretch between ski trips.
- Out-of-state owners need a vacation home policy, not a standard homeowner form built for a primary residence.
- Wood stove chimneys and short-term rental use each need a specific endorsement most base policies skip.
Why this matters
Ski chalets and mountain camps across New Hampshire's White Mountains and Lakes Region foothills sit on ground a standard Concord or Portsmouth homeowners form was never priced for. The state's 48 peaks above 4,000 feet mean heavier snow load on rooflines, longer stretches of sub-32°F pipe-freeze weather, and driveways that don't get plowed the same day as the rest of town.
Most of these properties are also heated, at least partly, by wood stove, a detail that changes how an underwriter prices the policy and what the fine print excludes. Add seasonal or part-time occupancy and you've got three risk factors a generic homeowners policy handles poorly: snow load, heat source, and vacancy. That's why owners of custom-built mountain homes often move to high-value home insurance for New Hampshire homeowners instead of a standard dwelling policy built around a generic per-square-foot rebuild formula.
Flood exposure near mountain streams and spring runoff is real too. Federal flood insurance through the NFIP caps out at $250,000 for the building and $100,000 for contents on a residential property, numbers that undersell a custom mountain home fast. None of this means a chalet is uninsurable in 2026. It means the policy has to match the property, not the other way around.
“A ski chalet that sits empty for weeks between visits needs a vacancy conversation with an agent before something goes wrong, not after.”
What makes the best home insurance for a New Hampshire ski chalet
- Dwelling coverage sized to true rebuild cost for high-elevation construction and materials
- Coverage that stays active through off-season vacancy, not just during peak occupancy
- Straightforward wood stove endorsement without a lengthy inspection backlog
- Flexibility for out-of-state or absentee ownership and remote claims handling
- Liability limits sized for guests, renters, and slope-adjacent activity on the property
- An option to add short-term rental coverage without rewriting the whole policy
New Hampshire ski chalet insurance options at a glance
| Option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| High-value home insurance | Chalets with high rebuild cost and custom finishes | Dwelling limit tracks true replacement cost | Underwriting is stricter and takes longer |
| Seasonal camp coverage | Chalets used only part of the year | Built around part-time occupancy patterns | Doesn't solve vacancy beyond the normal season |
| Vacant home coverage | Properties empty for stretches between trips | Keeps protection active with nobody checking in | Costs more than an occupied-home policy |
| Vacation home insurance for out-of-state owners | Owners who live outside New Hampshire | Built for remote management and infrequent visits | Claims response can be slower without a local contact |
| Wood stove endorsement | Chalets heated primarily by wood stove | Closes the fire and liability gap standard forms skip | Usually requires a chimney inspection first |
| Short-term rental insurance | Chalets rented out during ski season | Covers guest liability a homeowners form excludes | Doesn't replace year-round personal coverage |
1. High-value home insurance: best for chalets with high rebuild costs
A standard homeowners policy prices your dwelling coverage off a formula built for typical New Hampshire construction. A ski chalet with vaulted ceilings, stone fireplaces, and timber framing doesn't fit that formula, and a rebuild after a fire or a heavy snow-load roof failure can run well past a standard policy's dwelling limit.
High-value home insurance for New Hampshire homeowners prices the dwelling closer to actual replacement cost and usually extends the same treatment to detached structures like a ski shed or bunkhouse.
High-value home insurance pros:
- Dwelling limit reflects true rebuild cost, not a generic per-square-foot average
- Higher liability limits often come standard rather than as an add-on
- Extended replacement cost options absorb post-disaster material and labor spikes
High-value home insurance cons:
- Underwriting is more detailed and can slow down the quote
- Premiums run higher than a standard policy on a comparable home
- Not every carrier offering it writes in every New Hampshire mountain town
Best for: owners of custom-built or architecturally distinctive mountain chalets.
Verdict: Buy if your chalet would cost noticeably more to rebuild today than a standard policy's dwelling limit assumes.
2. Seasonal camp coverage: best for chalets used only part of the year
A lot of New Hampshire mountain properties aren't lived in year-round. They get heavy use from December through March, then sit mostly quiet. A policy written for a primary residence assumes someone's home most nights, which isn't how a ski chalet actually operates.
Guidance on insuring a seasonal camp in New Hampshire walks through how seasonal-use policies structure occupancy expectations differently than a standard homeowners form.
Seasonal camp coverage pros:
- Priced and structured around genuine part-time occupancy
- Often pairs well with wood stove and pipe-freeze protection
- Fits how most ski chalets are actually used through the year
Seasonal camp coverage cons:
- Still needs a vacancy conversation if the off-season stretch runs long
- Fewer carriers specialize in this form than in standard homeowners policies
Best for: owners who use the chalet heavily in winter and rarely otherwise.
Verdict: Buy if your chalet's occupancy pattern looks nothing like a year-round primary home.
3. Vacant home coverage: best for chalets empty for stretches between trips
Most standard homeowners policies include a vacancy clause that limits or suspends certain coverage once a home sits unoccupied past a defined stretch. A ski chalet that only gets visited every few weekends can trip that clause without the owner realizing it until a pipe bursts or a break-in happens.
A plan for insuring a vacant home in New Hampshire keeps water damage, theft, and vandalism coverage active during the gaps a standard policy would otherwise restrict.
Vacant home coverage pros:
- Keeps protection active during extended stretches with nobody on site
- Covers common vacancy risks: freeze damage, theft, vandalism
- Removes the guesswork around when a standard policy stops applying
Vacant home coverage cons:
- Costs more than a comparable occupied-home policy
- Doesn't add value if the chalet is genuinely occupied most weekends
Best for: owners who visit infrequently or leave the property empty for a full off-season.
Verdict: Buy if the chalet realistically sits empty more than a few weeks at a time.
4. Vacation home insurance for out-of-state owners: best for absentee ownership
A large share of New Hampshire ski chalets are owned by people who live in Massachusetts, Connecticut, or further away and drive up for weekends. That ownership pattern creates practical problems a standard local homeowners policy doesn't anticipate: who checks on the property, who's the local contact after a storm, and how fast a claim gets handled when the owner is three hours away.
Vacation home insurance for out-of-state owners builds those realities into the policy instead of treating them as exceptions.
Vacation home insurance pros:
- Structured for infrequent, planned visits rather than daily occupancy
- Local claims handling doesn't depend on the owner being on-site
- Often bundles cleanly with vacancy and wood stove endorsements
Vacation home insurance cons:
- Premiums can run higher than an in-state primary residence policy
- Still requires the owner to arrange someone local for checks and emergencies
Best for: chalet owners whose primary residence is outside New Hampshire.
Verdict: Buy if you're managing the property from another state and visiting on a schedule.
5. Wood stove endorsement: best for chalets heated primarily by wood stove
Wood stoves are common in New Hampshire mountain properties, both as a primary heat source and a backup during power outages. Many standard policies either exclude wood stove-related fire claims outright or require a specific endorsement and a chimney inspection before binding coverage.
A dedicated wood stove endorsement closes that gap rather than leaving it as a surprise at claim time.
Wood stove endorsement pros:
- Closes a fire and liability gap most base policies don't cover
- Chimney inspection requirement catches maintenance issues before they cause a fire
- Usually a low-cost add-on relative to the coverage gap it closes
Wood stove endorsement cons:
- Requires scheduling and passing a chimney inspection
- Adds a step to the underwriting process versus a stove-free property
Best for: any chalet where the wood stove is more than decorative.
Verdict: Buy if the stove gets used regularly through the winter, not just on cold weekends.
6. Short-term rental insurance: best for chalets rented out during ski season
Renting the chalet out on Airbnb or VRBO during peak ski weeks brings in income, but it also brings in guests a standard homeowners policy typically won't cover for liability. Most homeowners forms exclude business or rental activity, which is exactly what short-term guest stays are.
Short-term rental coverage adds guest liability protection specific to paid stays, on top of the personal coverage the owner already carries.
Short-term rental insurance pros:
- Covers guest injury and liability claims a standard policy excludes
- Can be scaled to how many weeks per year the property is actually rented
- Keeps the personal homeowners policy intact for non-rental periods
Short-term rental insurance cons:
- Adds a line item to the annual premium
- Requires accurate reporting of rental frequency to stay properly covered
Best for: owners renting the chalet out for any part of ski season.
Verdict: Buy if the property gets listed for even a handful of weekends a year.
How we ranked these options
Each option above was ranked against the same six criteria: rebuild cost accuracy, vacancy handling, wood heat coverage, ownership flexibility, liability sizing, and rental compatibility. None of these six scored well on all six; that's the point of a decision tree instead of a single leaderboard winner. A chalet with high-end finishes, seasonal use, absentee ownership, and a wood stove will realistically need two or three of these layered together, not just one policy.
If the mountain property also sits on a lake, the calculus shifts slightly toward water-adjacent risks; the guide to homeowners insurance for New Hampshire lake properties covers that scenario in more depth.
Get a quick review of your chalet’s coverage
Call or text to compare options for your specific property.
Which home insurance fits your New Hampshire ski chalet?
For most owners, the answer starts with rebuild cost. If a standard policy's dwelling limit wouldn't cover what it actually costs to rebuild a custom mountain chalet in 2026, high-value home insurance is the right starting point, and everything else layers on top of it.
From there, match the add-ons to how the property is actually used: seasonal camp coverage or vacant home coverage for occupancy gaps, an out-of-state vacation home policy for absentee owners, a wood stove endorsement for anyone burning wood regularly, and short-term rental coverage the moment the property gets listed for paid stays. Skipping the coverage that matches actual use is the most common and most expensive mistake mountain property owners make in 2026.
FAQ
What’s the best home insurance for a ski chalet in New Hampshire?
High-value home insurance is the best starting point for a New Hampshire ski chalet with a rebuild cost above what a standard policy assumes. Owners then layer on vacancy, wood stove, or rental coverage based on how the property is actually used.
Is high-value home insurance worth it for a mountain chalet?
It’s worth it once the chalet’s rebuild cost exceeds what a standard homeowners policy’s dwelling limit assumes for a typical New Hampshire home. Custom finishes, stone construction, and timber framing usually push that cost higher than a generic formula accounts for.
Does a standard homeowners policy cover a chalet with a wood stove?
Often not fully. Many standard policies exclude or limit wood stove-related fire claims unless a specific endorsement and chimney inspection are added first.
How long can a New Hampshire chalet sit vacant before coverage is affected?
Standard homeowners policies typically include a vacancy clause that limits certain coverage once a home sits unoccupied past a set stretch, which varies by carrier. Vacant home coverage removes that guesswork for properties that sit empty for weeks at a time.
Do out-of-state owners need a different policy for a New Hampshire vacation home?
Yes. Vacation home insurance for out-of-state owners is built around infrequent visits and remote management, which a standard local homeowners policy doesn’t account for.
Does home insurance cover renting out a ski chalet on Airbnb?
A standard homeowners policy generally excludes liability from paid short-term rental activity. Short-term rental insurance adds that guest liability coverage on top of the existing personal policy.
How much flood insurance does a mountain property in New Hampshire need?
Federal flood insurance through the NFIP caps residential coverage at $250,000 for the building and $100,000 for contents, which often isn’t enough for a high-value custom chalet. Owners of higher-value mountain homes typically discuss excess flood coverage on top of the NFIP limit.
What’s the biggest coverage gap for New Hampshire ski chalets?
The most common gap in 2026 is a policy that doesn’t match actual occupancy: a primary-residence homeowners form applied to a property that’s really vacant half the year, heated by wood stove, and occasionally rented out.
One last thing
The detail owners overlook most often isn't the dwelling limit, it's the chimney inspection tied to the wood stove endorsement. Skipping it doesn't just risk a denied claim after a fire; it can flag the whole policy for review at renewal. Book the inspection before binding coverage, not after the first cold snap of the season.